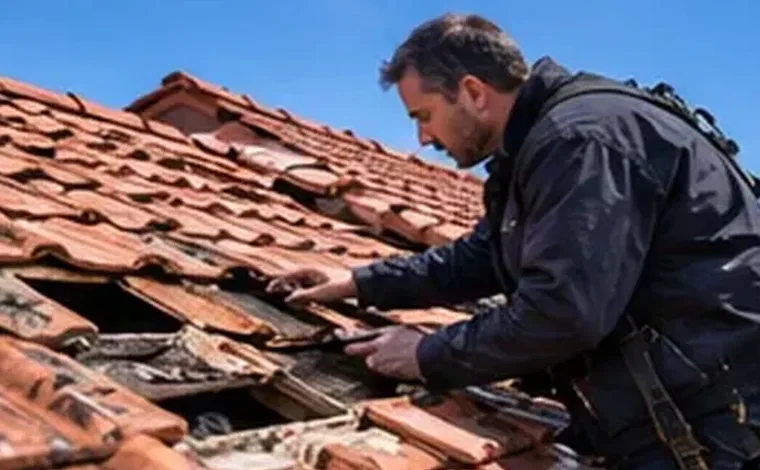
Scope of work on a wind claim
A hurricane or windstorm claim usually combines roof damage, interior water intrusion through the damaged envelope, fallen trees, fences and outbuildings, and sometimes additional living expense. The fee generally covers policy analysis, inspection with roof measurements and moisture readings, a repair estimate priced for post-storm conditions, contents documentation, the proof of loss, re-inspections with the carrier and negotiation.
Where storm surge or rising water also entered the property, a separate flood claim exists. A good contract clarifies whether the adjuster handles both claims and how each is billed.
Post-storm pricing matters. Labor and material costs typically rise after a major hurricane, and estimates based on pre-storm price lists can understate the real cost of repairs. Documenting current local pricing is part of what the fee pays for.
Indicative fee tiers on storm losses
The table gives an order of magnitude observed on the US market. It is not official and is overridden by any applicable state cap. Percentages decline as the claim grows, and many coastal claims after a named storm fall under emergency-specific limits for a set period.
| Amount recovered (USD) | Indicative fee | Typical storm claim |
|---|---|---|
| Up to 25,000 | 10% to 20%, depending on state caps | Roof repair, fence, minor interior damage |
| 25,001 to 100,000 | 10% to 15% | Roof replacement with interior water damage |
| 100,001 to 500,000 | 8% to 12% | Severe residential damage, contents and living expense |
| 500,001 to 2,000,000 | 6% to 10% | Large home or small commercial building |
| 2,000,001 to 10,000,000 | 3% to 7% | Condominium association, retail or office |
| Over 10,000,000 | Negotiated, often 1% to 3% | Hotel, industrial or multi-site portfolio |
Indicative amounts, to be checked with each expert.
Emergency caps in coastal states
Coastal states often regulate public adjusters tightly after hurricanes. Florida applies a lower fee cap to claims arising from a declared state of emergency for a period after the declaration, and a higher cap otherwise. Texas limits compensation to 10 percent of the settlement. Several states also forbid solicitation for a period after the event, require a cancellation window and impose contract wording rules. Confirm the current rules with your state Department of Insurance before signing, since legislatures revise them frequently.
How the deductible changes the fee
Many coastal homeowners policies carry a hurricane or named storm deductible expressed as a percentage of the dwelling limit, often in the range of a few percent. On a 400,000 dollar dwelling limit, a 2 percent deductible is 8,000 dollars, and a 5 percent deductible is 20,000 dollars.
The adjuster's fee normally applies to the amount actually paid, which is after the deductible. On a smaller claim, the deductible can absorb much of the value, leaving little room for an additional recovery that would justify a percentage fee.
A practical check: subtract the deductible from a contractor's realistic repair bid, compare the result with the insurer's offer, and apply the proposed fee to the difference. If the expected gain barely exceeds the fee, representation may not be justified.
Ways of calculating the fee
Look beyond the headline percentage and check what it is applied to.
- Percentage of all payments on the claim, including early advances
- Percentage of the amount recovered above the insurer's first estimate
- Separate rate for a reopened or supplemental claim
- Flat fee for a roof-only or limited-scope claim
- Hourly rate for engineers or roofing consultants retained by the adjuster
- Expense reimbursement, which should be capped or pre-approved
Supplemental claims and reopened files
Hidden storm damage often appears months later, when leaks show or contractors open walls. Many policies and state laws limit the time for reopening or supplementing a claim. Ask whether the original fee extends to supplemental payments, and whether the adjuster will handle them.
Work increases with the number of buildings, a dispute over wind versus flood causation, engineering reports alleging pre-existing damage, tile or metal roofs that are hard to match, and code upgrades requiring permits. A claim where the carrier accepts roof replacement early is far quicker. A firm that understands these drivers should be able to justify its proposed rate rather than quote a single figure for every claim.
Reimbursement through the policy
US homeowners policies rarely reimburse the cost of the policyholder's own adjuster. State wind pools, such as Citizens Property Insurance Corporation in Florida or the Texas Windstorm Insurance Association, follow their own policy forms and do not generally pay public adjuster fees either. In appraisal, each side usually pays its own appraiser and shares the umpire's cost.
For businesses, a claim preparation or professional fees provision may reimburse accountants preparing income figures, but rarely the public adjuster.
Examples across claim sizes
Roof and interior ceiling damage, 30,000 dollars paid after an 8,000 dollar deductible: at 10 percent, the fee would be 3,000 dollars. Whether this is worthwhile depends on how far the insurer's estimate sits below a reputable roofer's bid.
Major structural and contents damage, 280,000 dollars: at 10 percent, the fee would be 28,000 dollars; on an increase-only basis at 15 percent, starting from a 190,000 dollar offer, it would be 13,500 dollars.
Condominium association with multiple buildings, 8 million dollars: rates are usually negotiated to the low or mid single digits, for example 3 to 5 percent, or 240,000 to 400,000 dollars. These are illustrations, not quotes.
Choosing a firm after a storm
After a large hurricane, adjusters may arrive from other states on emergency licenses. Verify the license, ask how many claims the firm is carrying, who will negotiate your file, and how long the firm expects to stay in the area. Compare at least two written proposals.
Ask how the firm communicates during a catastrophe, when phone networks and offices may be disrupted, and who your backup contact is if the assigned adjuster leaves the area.
- Refuse contracts signed under pressure at the doorstep
- Be wary of any offer to cover or waive your deductible
- Ask how roof matching and code upgrades will be handled
- Confirm how fees are taken from joint checks with your mortgage lender
Organisations offering this service
- NAPIA – National Association of Public Insurance Adjusters: US professional association of public adjusters, founded over 75 years ago, offering a directory to find a member public adjuster near you.
- Adjusters International: US network of public adjusting firms representing policyholders, businesses and public entities in the settlement of significant property insurance claims.
- Noble Public Adjusting Group: Public adjusting firm operating nationwide across the United States, advocating for policyholders on residential and commercial property insurance claims.
- United Policyholders: US non-profit organisation that informs and supports policyholders after a loss, working alongside the public adjusting profession and its associations.
External links provided for information only; check the terms directly with each organisation.
Frequently asked questions
Are public adjuster fees lower after a declared hurricane?
In some states, yes. Lower caps often apply to claims tied to a declared emergency for a period after the declaration.
Does the fee apply to my deductible?
Normally not, since the fee applies to amounts paid by the insurer, which are net of the deductible. Confirm the wording in your contract.
Can I cancel a contract I signed in a hurry?
Many states provide a short cancellation window. Check the contract and state law, and send notice in writing.
Will the same adjuster handle my flood claim?
Only if the contract says so. Wind and flood claims are often separate, with different carriers and fee terms.
Storm season puts policyholders under pressure; a clear fee base, a verified license and a look at your deductible make the decision more rational. expertdassure.com covers the claims process itself on a companion page.