What insurers mean by a storm
Many policies, especially in the UK and Ireland, cover storm damage but do not define a storm in a single universal way. Insurers often look for evidence of unusually strong winds, heavy rainfall or hail around the date of the loss, and complaint bodies have historically considered whether weather conditions were genuinely exceptional and whether the storm was the main cause of the damage.
In the United States and Canada, wind and hail are usually named perils under homeowners policies, but deductibles may differ: some regions apply a separate wind or hail deductible, sometimes as a percentage of the dwelling sum insured. In Australia, storm cover is standard on most home policies, with detailed definitions distinguishing storm, rainwater runoff and flood.
Weather records as evidence
Because the existence and severity of the storm can be challenged, it helps to collect weather data for your location and date: national meteorological service reports, local weather station readings, hail-size reports, news coverage and photos from neighbours. A policyholder's expert can assemble these into a short chronology that links the event to the damage.
How the damage is inspected
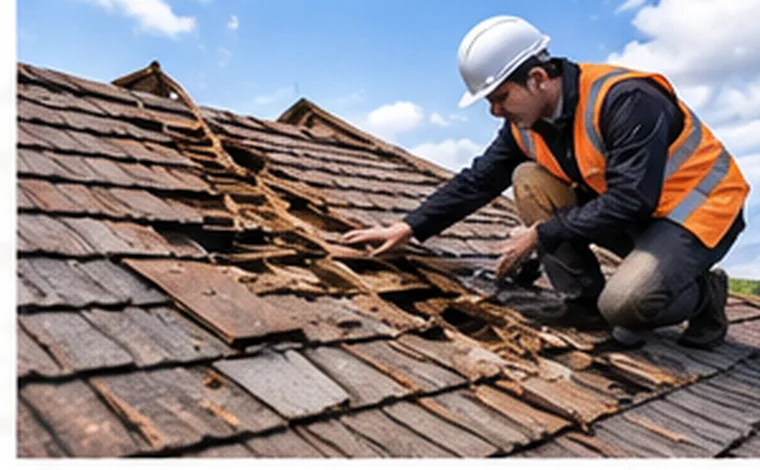
The insurer's adjuster or roofing contractor will inspect roof coverings, gutters, flashings, chimneys, windows, cladding, fences and outbuildings. For hail, they look for characteristic impact marks: bruised or fractured shingles, dented metal, cracked tiles and granule loss. Increasingly, drones and aerial imagery are used, particularly after widespread events.
Inside, they will look for water staining, saturated insulation, damaged ceilings and electrical risks caused by rain entering through the damaged envelope. Make sure all affected areas are shown, including attics and voids.
Ask for a copy of the inspection report or roof estimate once it is available. Desk-based assessments built from aerial photos can miss fractured tiles, lifted ridge lines or damage on slopes the camera did not capture clearly. If the report understates what you can see, a second inspection by an independent roofer, with dated photographs marked against a roof plan, gives you something concrete to put back to the insurer.
Documenting a storm or hail loss
Good documentation gives the adjuster less room to attribute damage to other causes.
- Photograph damage as soon as it is safe, including close-ups of hail impacts and wider shots for context
- Keep a few hailstones in a freezer or photograph them next to a coin or ruler
- Retain fallen tiles, slates, shingles or pieces of cladding
- Record emergency measures such as tarpaulins, boarding and water extraction, with receipts
- Gather any earlier roof inspections, maintenance invoices or photos showing the condition before the storm
Pricing roof and envelope repairs
Repairs to roofs and exterior surfaces raise questions that do not arise elsewhere. Matching new tiles or shingles to an existing, weathered roof may be impossible, and partial repairs can leave a visibly patched appearance or compromise warranties. Access costs such as scaffolding and safety equipment can represent a large share of the bill.
An estimate prepared for the insured should specify the extent of replacement, the materials, access arrangements and associated internal repairs. Where building regulations require upgrades when a roof is re-covered, such as improved insulation or underlayment, it is worth checking whether the policy pays for compliance costs.
Wear and tear versus storm damage
The most common reason for declining or reducing a storm claim is the assertion that damage was caused by gradual deterioration, defective workmanship or lack of maintenance, with the storm merely revealing it. Policyholders can respond with evidence of the roof's previous condition, expert opinion on how the damage pattern fits the reported wind or hail and, where possible, a comparison with similar damage to neighbouring properties hit by the same event.
Other typical disagreements
Beyond causation, insurers and policyholders often disagree over full versus partial roof replacement, cosmetic hail dents on metal roofs, which some policies exclude, the cost of matching materials, depreciation on older roofs and the coverage of fences, sheds and garden structures, which may have lower limits or none at all.
Bringing in a policyholder's expert
An independent expert, whether a public adjuster, loss assessor or experienced claims consultant, is worth considering when the claim has been declined on wear-and-tear grounds, when the insurer proposes a patch repair you believe is inadequate, or when water ingress has caused extensive interior damage. They can obtain specialist roofing reports, challenge the insurer's estimate and handle the negotiation.
After big storms, beware of contractors or canvassers offering to deal with your insurer in exchange for signing a repair contract immediately. Confirm licences where applicable, read any assignment or engagement documents carefully, and understand the fee before agreeing. Ombudsman schemes in the UK, Ireland and Australia, and appraisal or regulators in North America, remain available if negotiation fails.
Organisations offering this service
- Financial Ombudsman Service: Official free dispute resolution service in the United Kingdom, handling complaints from policyholders against insurers, including disputed or rejected insurance claims.
- Chartered Institute of Loss Adjusters (CILA): Chartered UK professional body for claims and loss adjusting professionals, responsible for training, qualifications and standards across the claims profession.
- Aspray: UK network of loss assessors handling and negotiating insurance claims on behalf of policyholders, notably after fire, flood and escape-of-water damage.
- Adjusters International: US network of public adjusting firms representing policyholders, businesses and public entities in the settlement of significant property insurance claims.
External links provided for information only; check the terms directly with each organisation.
Frequently asked questions
My claim was refused because the insurer says there was no storm. What can I do?
Request the weather data the insurer relied on, collect your own records from local stations and news reports, and ask for the decision to be reviewed. If it stands, you can use the formal complaint route.
Is hail damage to my car covered by home insurance?
No. Vehicle damage is usually handled under a motor policy with comprehensive or equivalent cover, not under home insurance.
Do I need to replace the whole roof if only part is damaged?
Not necessarily. It depends on the extent of the damage, the availability of matching materials and the policy terms. A specialist report can support a request for wider replacement.
Storm and hail claims are often decided on the question of causation. Gather weather evidence and pre-loss records, and consider expert support if the insurer points to wear and tear; expertdassure.com explains each option in more depth.